
Buying a subsale house gives you the opportunity to see the actual property, assess its condition, explore the neighbourhood, and compare recent transaction prices before committing to a purchase. However, buying from an existing owner involves a different process from purchasing a new property directly from a developer.
You will need to budget for the deposit and other upfront costs, arrange financing, conduct legal checks, inspect the property, sign the Sale and Purchase Agreement (SPA), and complete the transfer before receiving vacant possession.
If you are considering a home in Malaysia’s secondary market, here are seven key steps to buying a subsale property in 2026.
Find properties for sale that match your needs and budget.What Is A Subsale House?
A subsale house is a property being sold by an existing owner rather than directly by the developer. It may be a landed house, condominium, apartment, or another completed residential property that has previously been purchased.
Unlike buying a property under construction, buyers can generally inspect the actual unit before making an offer. This makes it easier to assess its condition, surroundings, layout, renovations, and potential repair costs.
However, subsale properties generally do not come with the developer’s defect liability period (DLP). Buyers should therefore conduct a thorough inspection and complete the necessary legal and financial checks before proceeding.
What Are The Pros And Cons Of Buying A Subsale House?
Buying a subsale house gives you more information about the actual property before you commit, but it can also involve additional costs and checks.
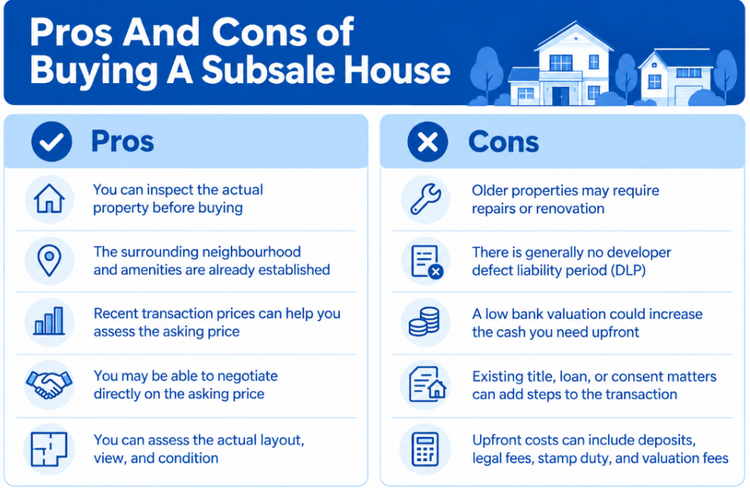
These factors make inspection, budgeting, price comparison, and legal checks particularly important when considering a subsale house.
If you are planning to buy a subsale house in Malaysia, understanding the process beforehand can help you prepare for the costs, paperwork, financing, and property checks involved.
Here are seven key steps to buying a subsale house in Malaysia.
Step 1: Calculate The Costs Of Buying A Subsale House
Before searching for a property, work out how much you can comfortably afford.
A subsale transaction commonly involves a 10% deposit, subject to the agreed terms and the amount the bank is prepared to finance. Buyers may first pay an earnest deposit when their offer is accepted, with the balance of the agreed deposit generally payable when the Sale and Purchase Agreement (SPA) is signed.
However, the deposit is only one part of your upfront budget.
Potential costs include:
| Cost | 2026 Rate / Estimated Amount | Important Information |
| Earnest deposit | Commonly around 2% to 3% of the purchase price | Usually paid upon signing the Letter of Offer or Booking Form after the price is agreed. It forms part of the overall deposit. Check the terms carefully to determine whether it is refundable if your housing loan is rejected. |
| Remaining deposit | Usually brings the total deposit to 10% of the purchase price | The balance is generally paid when the Sale and Purchase Agreement (SPA) is signed. The actual amount depends on the agreed terms and financing obtained. |
| Transfer stamp duty | First RM100,000: 1%; RM100,001 to RM500,000: 2%; RM500,001 to RM1 million: 3%; Above RM1 million: 4% | Calculated on the relevant property value for stamp duty purposes. A RM750,000 property, for example, would attract RM16,500 in transfer stamp duty before any applicable exemption. |
| Loan agreement stamp duty | 0.5% of the loan amount | A RM450,000 housing loan would generally attract RM2,250 in loan agreement stamp duty before any applicable exemption. |
| SPA stamp duty | RM10 per copy | This is separate from the much larger transfer stamp duty payable on the transfer instrument. |
| SPA legal fees | First RM500,000: 1.25%; next RM7 million: 1% | Governed by the Solicitors’ Remuneration Order 2023 for the applicable sale and transfer transaction. Additional tiers apply for higher values. |
| Loan legal fees | Scale fees apply based on the financing amount | If you take a housing loan, legal work for the financing documentation is an additional cost to the purchase conveyancing fees. |
| Valuation fee | Based on the property’s assessed value and applicable professional fee scale | Banks commonly require a valuation for a subsale property before finalising financing. The valuation can also affect how much the bank is prepared to lend. |
| Insurance or takaful | Varies by product, coverage, loan amount, age, and financing package | Mortgage protection and property-related insurance costs are not a fixed percentage of the purchase price, so obtain an actual quotation rather than using a standard estimate. |
| Legal disbursements and registration costs | Varies by transaction | May include registration fees, land searches, bankruptcy searches, transport, and other properly incurred transaction expenses. |
| Repairs and renovation | Depends on the property’s condition | Unlike a new property, a subsale house may require immediate repairs, replacement of fittings, repainting, or renovation. Inspect the property before setting your budget. |
Under the Solicitors’ Remuneration Order 2023, the scale fee under Table A for a sale and transfer is 1.25% on the first RM500,000 and 1% on the next RM7 million. Legal fees are separate from items such as stamp duty, registration fees, valuation fees, searches, and other applicable disbursements.
Can First-Time Homebuyers Get A Stamp Duty Exemption In 2026?
Yes, subject to the qualifying conditions.
Under Budget 2026, Malaysian citizens purchasing their first residential home priced up to RM500,000 can receive a 100% stamp duty exemption on the instrument of transfer and loan agreement. The extension applies to SPAs executed from 1 January 2026 to 31 December 2027.
Eligible first-home buyers may also want to check the separate income tax relief available for interest paid on a housing loan. For qualifying first residential properties with SPAs executed from 1 January 2025 to 31 December 2027, the relief is capped at RM7,000 for homes up to RM500,000 and RM5,000 for homes above RM500,000 and up to RM750,000.
Budget For A Possible Valuation Shortfall
One cost that subsale buyers can overlook is the difference between the agreed purchase price and the property’s bank valuation. For financing purposes, the bank will assess the property’s market value, and the approved loan may be based on the lower value rather than simply on the price you agreed with the seller.
For example, if you agree to buy a property for RM600,000 but the bank values it at RM550,000, a 90% margin of financing based on the valuation would provide a loan of RM495,000. You would need to cover the remaining RM105,000 yourself, before accounting for legal fees, stamp duty, valuation fees, and other costs.
This makes checking recent transaction prices and keeping an additional cash buffer particularly important when buying a subsale house.
Step 2: Choose The Right Subsale Property And Inspect It Carefully
Once you have established your budget, shortlist properties based on factors such as:
- Location and neighbourhood
- Property type and built-up size
- Freehold or leasehold tenure
- Remaining lease, where applicable
- Accessibility and transport links
- Schools, healthcare, shops, and other amenities
- Maintenance charges and sinking fund contributions for strata properties
- Property condition and likely repair costs
One major advantage of buying a subsale property is that you can inspect the actual unit.
Look for signs of water leakage, cracks, damaged flooring, plumbing or electrical problems, roof issues, poorly maintained fixtures, and unauthorised alterations. For older or extensively renovated properties, consider engaging an appropriate professional to inspect the property.
For a strata property, buyers can also ask about maintenance charges, sinking fund contributions, house rules, parking arrangements, and the general management of the development.
What Legal Checks Should You Make Before Buying?
Your lawyer plays an important role in conducting due diligence before the transaction is completed.
Depending on the property, relevant checks can include verifying the registered proprietor, title particulars, restrictions in interest, existing charges or encumbrances, and whether consent is required for the transfer.
Do not assume that the person marketing the property is automatically entitled to sell it. Ownership and title details should be properly verified as part of the conveyancing process.
Stay informed about Malaysia’s property market with Property Insights.Step 3: Check The Market Value Before Making An Offer
Before agreeing to the seller’s asking price, check how much similar properties have actually sold for. Asking prices show what sellers hope to receive, while past transaction data can provide a useful reference for prices achieved in previous sales.
When comparing properties, look at characteristics that can influence their value, including:
- Property type and development
- Built-up or land area
- Freehold or leasehold tenure
- Transaction date
- Floor level or unit position, where relevant
- Property condition and renovations
For example, if comparable units in the same condominium have recently transacted between RM500,000 and RM530,000, a seller asking RM600,000 may warrant a closer look. A larger layout, extensive renovations, unit position, or other features could explain the difference.
What Should You Know About Property Valuation?
If you are applying for a housing loan, the bank will generally appoint a panel valuer to assess the property. The valuation can affect how much the bank is prepared to finance.
For example, if you agree to buy a house for RM600,000 but it is valued at RM580,000, 90% financing based on the valuation would amount to RM522,000. You would need to cover the difference between the purchase price and approved financing yourself, in addition to other upfront costs.
How To Check Subsale Transaction Prices On iProperty
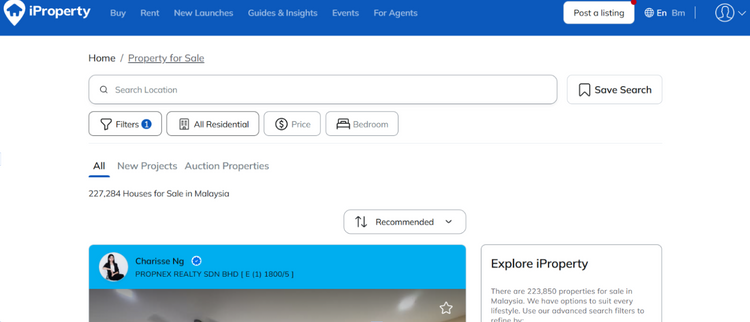
You can use the iProperty Transactions Section to explore historical residential property transactions in Malaysia and compare properties in your preferred area.
Step 1: Search for the location, neighbourhood, or development you are interested in.
Step 2: Refine the results using available filters, such as property type, tenure, and price.
Step 3: Compare recent transaction prices and available information, such as price per sq ft, across similar properties.
Use several comparable transactions rather than relying on a single sale. Transaction data can help you assess the asking price and negotiate more confidently, but it should be used as a reference rather than treated as a formal property valuation.
Step 4: Make An Offer And Apply For A Housing Loan
Once you have found the right property and agreed on a price, the next stage generally involves making a formal offer and paying the agreed earnest deposit.
Read the Letter of Offer or booking document carefully before signing it. Pay particular attention to the purchase price, deposit, deadline for signing the SPA, items included in the sale, and what happens to the deposit if financing is not approved.
Do not assume an earnest deposit will automatically be refunded if your loan application fails. The outcome depends on the terms you agreed to.
You can then compare housing loans from different banks based on factors such as:
- Margin of financing
- Effective lending rate
- Monthly repayment
- Loan tenure
- Lock-in period, where applicable
- Early settlement conditions
- Flexi or redraw features
- Insurance or takaful requirements
For new retail floating-rate loans, Malaysia uses the Standardised Base Rate (SBR), which is linked to Bank Negara Malaysia’s Overnight Policy Rate (OPR). The spread charged above the SBR can vary according to the bank and borrower.
From 1 July 2026, Bank Negara Malaysia’s revised Reference Rate Framework also strengthens requirements for banks to reflect reference-rate changes promptly and provide clearer information when monthly instalments or financing tenures are adjusted.
Calculate your estimated monthly repayments with the Mortgage Calculator.Step 5: Sign The Sale And Purchase Agreement And Confirm The Inventory
Once the purchase terms are agreed, your lawyer will prepare or review the Sale and Purchase Agreement (SPA). Before signing, check that the SPA accurately reflects the property and everything agreed with the seller.
Pay particular attention to:
- Purchase price and deposit: The SPA should record the agreed price and payment terms. It is usual for the deposit to total 10%, less any earnest deposit already paid.
- Completion period: Check when the balance purchase price must be paid and what happens if completion is delayed.
- Property details: Make sure the title particulars, unit or property description, and any associated parcel such as a car park are correctly recorded.
- Vacant possession: Confirm when and under what conditions the property will be handed over.
- Outstanding outgoings: The SPA should address items such as quit rent, assessment, maintenance charges, and other applicable outgoings.
- Special conditions: If the sale depends on consent, redemption of the seller’s existing loan, an existing tenancy, or another condition, make sure the relevant provisions are included.
Prepare A Detailed Inventory List
Do not rely on what you saw during the viewing or on verbal promises about what will remain in the house. Prepare an agreed inventory covering items such as air conditioners, fans, lights, built-in cabinets, furniture, appliances, access cards, and other fixtures or fittings included in the sale.
The Malaysian Bar recommends giving this inventory to your lawyer so it can be attached to the SPA, helping to prevent misunderstandings when the transaction is completed.
It can also be useful to photograph important items and the property’s condition before signing. When you inspect the property again before vacant possession, you can check that the agreed items are still present and that any specific obligations agreed with the seller have been met.
Step 6: Sign The Loan Documents And Complete The Property Transfer
Once your housing loan is approved, you will need to sign the loan or financing documents. Check the approved amount, interest or profit rate, loan tenure, monthly instalment, and other conditions before signing.
What happens next depends partly on the property’s title status.
1. If The Individual Or Strata Title Has Been Issued
For a property with an individual or strata title, the seller generally signs a Memorandum of Transfer (MOT), also known as Form 14A, to transfer the property to you.
If you are financing the purchase, a charge over the property is also registered in favour of your bank. Once the required documents, stamp duty, and registration requirements are completed, the transfer and new charge can be presented to the relevant land office or registry.
2. If The Individual Or Strata Title Has Not Been Issued
If the property is still held under a master title, the transfer process is different. A Deed of Assignment (DOA) may be used to assign the seller’s rights and interests in the property to you, subject to the circumstances of the transaction.
Your bank may also take an assignment of your rights in the property as security for the housing loan.
3. What If The Seller Still Has A Housing Loan?
This is common with subsale properties. The seller’s bank will issue a redemption statement showing how much remains outstanding on the existing loan.
Part of your purchase funds or housing loan may then be used to settle this redemption sum. For a titled property, the seller’s existing charge must be discharged so that the transfer and your bank’s new charge can proceed. For a property without an individual or strata title, the existing financing security generally needs to be reassigned or released through the applicable documentation.
If your approved housing loan does not cover the full purchase price, you will also need to pay the difference from your own funds before the bank releases the financing according to the transaction requirements.
Your lawyer and the bank’s lawyer will coordinate these steps, including the relevant documents, stamp duty, registration, redemption, and release of the financing.
Step 7: Take Vacant Possession And Collect The Keys
The final stage is vacant possession (VP), when the property is handed over to you after the relevant completion requirements under the SPA have been met.
Subsale SPAs commonly provide a completion period of around three months, with an additional period sometimes available subject to the terms of the agreement and applicable interest. The exact timeline should always be checked against your SPA.
Before or during handover, check:
- Keys, access cards, and remotes
- Fixtures and fittings listed in the inventory
- Utility arrangements
- Maintenance and sinking fund payments
- Quit rent and assessment-related matters, where applicable
- Condition of the property compared with what was agreed
- Any agreed apportionment of charges between buyer and seller
Conduct a final inspection before taking possession where possible. If something that should have remained in the property is missing, or its condition differs materially from what was agreed, raise the issue promptly with your lawyer.
Once the transaction is completed and the keys have been handed over, you can begin preparing the property for occupation.
Search properties for rent in Malaysia and compare available homes.How Long Does It Take To Buy A Subsale House In Malaysia?
For many subsale transactions, the SPA provides around three months from the date of the agreement for the buyer to pay the balance purchase price. Depending on the SPA, an extension of about one month may be available, usually with late payment interest.
However, this does not mean every subsale house purchase will be completed within three months. The timeline may be longer if the transaction requires:
- State authority consent, particularly where the title contains a restriction in interest
- Redemption of the seller’s existing housing loan before the property can be transferred
- Developer or relevant consent for properties where an individual or strata title has not been issued
- Additional loan documentation or conditions before the buyer’s bank releases the financing
- Title or registration matters that must be resolved before completion
For example, if state authority consent is required, the SPA may provide that the completion period only starts after the necessary consent has been obtained rather than simply from the date the SPA is signed.
Before planning your move, ask your lawyer which approvals apply to the particular property and when the completion period under your SPA actually begins. This will give you a more realistic handover timeline than assuming that every subsale purchase takes exactly three months.
What Should You Check Before Buying A Subsale House?
A subsale property lets you assess much more than its floor plan. Before committing, use this quick checklist:
- Confirm that the asking price is reasonable against recent transactions.
- Check the title, tenure, ownership, and relevant restrictions.
- Inspect the property’s physical condition.
- Calculate your deposit and other upfront costs.
- Estimate whether a valuation shortfall would affect your budget.
- Review maintenance charges and sinking fund contributions for strata properties.
- Confirm exactly which fixtures and fittings are included.
- Read the offer documents and SPA carefully before signing.
- Understand the financing terms and monthly repayment.
- Keep additional cash available for repairs, renovation, and unexpected expenses.
Completing these checks before committing to a subsale house can give you a clearer picture of its true cost, condition, and legal status. It can also help you identify potential issues early, negotiate with better information, and avoid unexpected expenses later in the purchase process.
Making An Informed Subsale Property Purchase
A subsale house may suit buyers who want to inspect a completed property, move into an established neighbourhood, and compare the asking price against actual transaction data before purchasing.
However, the condition of the property, financing, legal documentation, title status, and upfront costs can vary considerably from one home to another.
Set a realistic budget before making an offer, inspect the property carefully, compare recent transactions, and have the necessary legal checks completed. Taking these steps can help you understand what you are buying and reduce the likelihood of unexpected costs during the transaction.
Looking for a newly launched home? Explore new properties in Malaysia and discover the latest developments for sale.