Buying a home in Malaysia involves more than comparing prices, locations, and layouts.
Buyers may also worry about construction defects, unclear developer responsibilities and what legal protection they have if something goes wrong after moving in. Understanding your rights before signing a purchase agreement can help you avoid costly surprises.
The Housing Development Act (HDA) provides specific protections for eligible home buyers purchasing properties from developers. It sets out requirements for developers and provides a framework for addressing issues such as defects during the defect liability period.
In this guide, we explain what the HDA is, the protections it offers, what to check during the defect liability period, and what you can do if defects are not repaired. We also cover non-HDA properties and properties that may be exempt, helping you understand what protection applies to your purchase.
<a href=”https://www.iproperty.com.my/guides/home-finance”><strong>Plan your home financing with our helpful guides.</strong></a>What is the Housing Development Act (HDA)?
The Housing Development Act (HDA), officially the Housing Development (Control and Licensing) Act 1966, protects buyers purchasing residential properties from licensed developers in Malaysia’s primary market. It applies to residential properties covered by the Act and safeguards buyers’ interests during the purchase and homeownership process.
Which properties are covered by the HDA?
The HDA generally covers residential properties bought directly from licensed housing developers, including:
- Landed residential properties such as terrace houses, semi-detached houses and bungalows
- Strata residential properties such as apartments and condominiums
- Other residential properties covered by the prescribed Sale and Purchase Agreement (SPA) schedules under the HDA
Buyers of strata properties also receive additional protection under the Strata Titles Act 1985 and the Strata Management Act 2013, which work alongside the HDA.
Which properties are exempt from the HDA?
Some properties and transactions fall outside HDA protection, including:
- Commercial properties such as offices, retail units and industrial properties
- SoFo and SoVo units, which are generally treated as commercial properties
- Properties bought on the secondary market from existing owners rather than directly from a developer
- Other property types or transactions that do not fall within the scope of the HDA and its prescribed SPA
If you’re unsure whether your purchase is covered, check your Sale and Purchase Agreement and the applicable SPA schedule before relying on HDA protections.
<a href=”https://www.iproperty.com.my/semi-d-for-sale”><strong>Explore semi-detached homes for sale across Malaysia. </strong></a>What happens if a property isn’t protected under the HDA?
Some properties fall outside HDA protection, so buyers must rely on other safeguards.
- Commercial and non-residential properties. Small office/flexible office (SoFo) and small office/versatile office (SoVo) units, office spaces, retail and industrial units all sit outside HDA protection.
- Secondary market properties. Subsale properties bought from a previous owner rather than a developer also don’t fall under the HDA, since the Act only covers primary market purchases.
- A quick way to check. Look at your Sale and Purchase Agreement; HDA properties use the standard Schedule G (for landed properties) or Schedule H (for high-rise properties).
- Exceptions worth knowing (Serviced apartments and SoHo units). Although these properties are built on commercial land, they are residential in purpose and can still fall under HDA protection.
However, quit rent, assessment rates and utilities may be charged at commercial rates, which can increase ongoing costs.
- What protects you instead? For non-HDA properties, protection depends on the non-standard SPA and its terms. Consider legal advice before signing, as disputes may need to go through the courts.
Knowing whether your property falls under the HDA affects what protections you can rely on and how you’d need to pursue a claim if something goes wrong, so it’s worth confirming this before you sign.
What protections does the HDA give home buyers?
For eligible residential property purchases, the HDA provides several protections that can help buyers understand their rights and hold developers accountable. Key protections include:
- Standardised sale and purchase agreements
The HDA requires developers to use prescribed sale and purchase agreement forms for covered residential properties. This helps set out the rights and obligations of both the buyer and developer in a consistent format.
- Defect liability protection
New homes covered by Malaysia’s prescribed housing sale-and-purchase agreements generally have a 24-month defect liability period (DLP) from vacant possession. During this period, developers must repair qualifying defects caused by faulty workmanship, materials, or construction, usually within 30 days of written notice.
- Protection against construction defects
If buyers identify defects covered by the agreement, they can notify the developer and request repairs. This can include issues affecting the property’s workmanship or construction.
- Developer licensing and regulation
Property developers covered by the HDA must meet licensing and regulatory requirements. This provides an additional layer of oversight for buyers purchasing from regulated developers.
- Access to the Tribunal for Homebuyer Claims
Eligible buyers may bring certain disputes against developers before the Tribunal for Homebuyer Claims. This offers a more accessible route for resolving qualifying claims without immediately pursuing court proceedings.
The HDA gives eligible home buyers a framework of contractual and legal protections, particularly around developer obligations and property defects. However, the extent of protection depends on whether the property and transaction fall within the Act’s scope.
What should you check for during the defect liability period?
The defect liability period is an important time for home buyers to inspect their property and report problems to the developer. Rather than waiting for obvious issues to appear, carry out a thorough inspection and document any defects you find.
- Walls and ceilings: Look for cracks, damp patches, water stains, uneven surfaces or signs of water seepage. Pay particular attention to areas around windows, bathrooms and ceilings.
- Doors and windows: Check that doors and windows open, close and lock properly. Look for damaged frames, gaps, loose fittings, or alignment issues.
- Flooring and tiles: Check for cracked, chipped, loose or uneven tiles. Walk across different areas to identify movement, hollow sounds or uneven surfaces.
- Plumbing and drainage: Test taps, sinks, showers and toilets for leaks, weak water flow or drainage problems. Check underneath sinks and around bathroom fittings for signs of water leakage.
- Electrical fittings: Test lights, switches, sockets, fans and other installed electrical fittings to make sure they operate properly. Report any exposed wiring or unusual electrical behaviour promptly.
- Paintwork and finishes: Look for peeling paint, stains, uneven finishing, gaps, damaged surfaces and other artistry issues.
- Kitchen and bathroom fittings: Inspect cabinets, countertops, sanitary fittings and other installed fixtures for damage, loose components or poor installation.
- Water seepage and leaks: Check for signs of moisture, particularly after rain or when using bathrooms and plumbing fixtures. Early detection can help prevent more extensive damage.
- Keep records of every defect, including photographs, videos, dates, and copies of correspondence with the developer. Submit your complaints through the required process and keep proof that you reported them.
A detailed inspection during the defect liability period can help you identify problems early and create a clear record for requesting repairs from the developer.
Estimate your monthly mortgage payments with our calculator.What can you do if a developer refuses to repair defects?
If a developer refuses to repair qualifying defects during the defect liability period, you can take several steps before paying for the repairs yourself.
- Start with the retention sum
A 5% retention sum is held by the developer’s solicitor to cover qualifying defects. If the developer fails to carry out repairs within the required period after receiving written notice, this sum may be used towards the repair costs.
- How do you file a claim?
The Ministry of Housing and Local Government (KPKT) provides the relevant TTPR forms, including the claim form and technical claim attachment. The claim form requires details such as the amount claimed, the basis of the claim, and the relevant dates.
For claims involving strata common property, such as defects in shared facilities, the Strata Management Tribunal may be the relevant forum instead, depending on the nature of the dispute. Its jurisdiction and claim limits differ from those of the TTPR.
- Consider the Tribunal for Homebuyer Claims
The Tribunal for Homebuyer Claims (TTPR) provides an alternative to court for disputes arising from a Sale and Purchase Agreement between a homebuyer and a licensed housing developer. It covers residential properties such as landed homes, apartments, condominiums, and SOHO units in Peninsular Malaysia and Labuan.
You can generally bring two types of claims:
- Technical claims: Defects in workmanship or materials, or construction that does not follow the plans and specifications in the SPA.
- Non-technical claims: Issues such as late delivery of vacant possession and other claims arising from the SPA.
- Know the RM50,000 limit
The TTPR can hear claims of up to RM50,000. If your claim exceeds this amount, it cannot generally be filed with the Tribunal unless you and the developer agree in writing to give the Tribunal jurisdiction over the higher amount. Otherwise, the claim would generally need to be pursued through the civil courts.
- Check the filing deadline
The deadline depends on the type of claim. Technical claims must generally be filed within 12 months from the end of the DLP.
Claims for liquidated ascertained damages (LAD) and other claims arising from the Sale and Purchase Agreement (SPA) must generally be filed within 12 months from the date the Certificate of Completion and Compliance (CCC) is issued. If the SPA was terminated before the CCC, the applicable period is generally 12 months from the termination date.
This means buyers should keep records of defects, written notices to the developer, repair requests, and relevant SPA documents rather than waiting until the deadline is close.
- Get technical defects assessed
For technical claims, the Tribunal may consider evidence of defects, workmanship, materials, and whether the property matches the agreed plans and specifications. Keep photographs, inspection reports, correspondence with the developer and repair quotations as supporting documents.
If repairs are not resolved, keep all evidence and check the appropriate claim route, limit and deadline before taking further action.
How is an HDA property different from a non-HDA property?
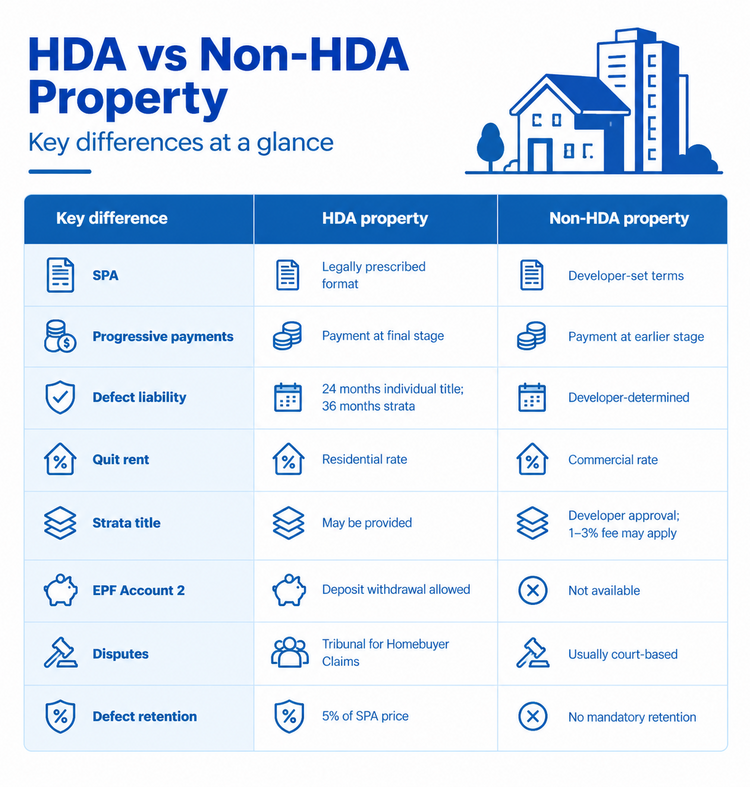
Buying a home comes with risks such as defects and delays. The Housing Development Act (HDA) protects buyers who purchase residential properties directly from licensed developers in Malaysia.
| Aspect | HDA property | Non-HDA property |
| Sale and Purchase Agreement | Follows a standard format set by law. | No standard format; each developer can set their own terms. |
| Progressive payments | Bank disburses payment at the final progressive stage. | Bank disburses payment at an earlier progressive stage. |
| Defect liability period | 24 months for individual title, 36 months for strata title, from the date you receive your keys. | Up to the developer to offer one, and for how long. |
| Quit rent | Charged at the flat rate for residential properties. | Charged at a higher commercial rate. |
| Strata title | May be included, depending on the development. | Requires approval from the developer, often with a 1-3% charge based on the SPA price. |
| EPF Account 2 withdrawal | Buyers can use EPF Account 2 savings to pay the deposit. | This option isn’t available. |
| Dispute resolution | Can be brought to the Tribunal for Homebuyer Claims. | Typically needs to go through the courts. |
| Retention sum for defects | Developer must hold 5% of the SPA price for repairs. | No such requirement. |
The HDA gives home buyers real recourse when things go wrong, from defect repairs to tribunal claims. Before signing your SPA, confirm whether your property falls under HDA protection; it could matter later.
Knowing whether a property falls under the HDA can help you understand the protections available to you as a buyer. HDA properties generally come with standardised safeguards, while non-HDA properties rely more heavily on the terms of the SPA. Check the property’s HDA status and your SPA before signing.