
Islamic home financing can look complicated on paper, particularly when familiar loan terms are replaced by concepts such as Murabahah, Tawarruq, and profit rates. For homebuyers, the challenge is to understand how these terms affect the financing structure, overall cost, and monthly repayments.
Islamic home financing is structured according to Shariah principles rather than an interest-based lending arrangement. Depending on the financing package, a bank may use structures such as Commodity Murabahah or Tawarruq to finance your property purchase.
This guide explains what Islamic home financing means, how it works, the common structures used in Malaysia, and how profit rates are determined. It also covers the costs, documents, and application steps you should understand before comparing your financing options.
Use the Mortgage Calculator to estimate your monthly repayments.What Is Islamic Home Financing?
Islamic home financing is a Shariah-compliant way to finance a property purchase. Instead of charging interest on a conventional home loan, the bank uses a Shariah-approved financing structure to earn a profit or other permissible return.
Islamic financing is already a significant part of Malaysia’s financial system. In 2025, Islamic financing accounted for 48% of total financing in Malaysia, according to Bank Negara Malaysia.
For a homebuyer, the main difference is how the financing is structured:
- Conventional financing: The bank lends you money and charges interest.
- Islamic financing: The bank uses a Shariah-compliant contract, such as Commodity Murabahah, to structure the financing and earn a profit.
For example, Maybank’s current Commodity Murabahah Home Financing-i uses a cost-plus-profit (Murabahah) structure involving the trading of Shariah-compliant commodities.
You do not have to be Muslim to apply for Islamic home financing. Eligibility depends on the bank and the specific product.
How Does Islamic Home Financing Work in Malaysia?
Once you have chosen a property and financing package, you submit your application and supporting documents for the bank to assess. For example, Maybank uses Commodity Murabahah for its Home Financing-i, while AmBank uses Tawarruq for its Home Financing-i.
- The bank assesses your financing application: The bank reviews your income, financial commitments and property details to determine whether you meet its financing requirements.
- The financing is structured using a Shariah contract: The bank uses a Shariah-compliant contract, such as Commodity Murabahah or Tawarruq, to structure the financing arrangement.
- The required transactions are carried out: Depending on the contract, the required sale, purchase or other contractual transactions are completed according to the agreed financing structure.
- The bank earns its profit from the financing: Instead of charging interest on a conventional loan, the bank earns a permissible return through the Shariah-compliant financing structure.
- You make monthly instalments: You make the agreed payments throughout the financing tenure, with the amount and payment terms depending on your specific financing facility.
- The financing is eventually settled: Once you have fulfilled your contractual payment obligations, the Islamic home financing facility is settled according to its terms.
The transaction structure, fees, profit calculation and settlement terms vary between products. Check the bank’s Product Disclosure Sheet (PDS) and financing agreement before accepting an offer.
Discover home financing tips for your next property with financing guides.What Types of Islamic Home Financing Are Available?
Islamic home financing can use different Shariah contracts. The structure depends on the bank and the specific financing product. Three terms you may come across are Commodity Murabahah/Tawarruq, Musharakah Mutanaqisah and Ijarah.
1. Commodity Murabahah or Tawarruq
Commodity Murabahah is a cost-plus-profit arrangement. Tawarruq involves a series of commodity sale transactions to facilitate financing.
2. Musharakah Mutanaqisah
Musharakah Mutanaqisah is based on partnership. The bank and customer share ownership of the property, while the customer’s ownership share increases as they make payments towards acquiring the bank’s share.
The exact arrangement, payment structure and documentation depend on the financing product.
3. Ijarah
Ijarah is a leasing-based structure. The arrangement involves the use of an asset in return for agreed payments, with ownership arrangements determined by the contract.
Not every bank uses the same Shariah structure. Before applying, check the bank’s PDS to understand the contract, payment structure and other terms.
Islamic Home Financing vs Conventional Home Loans
Both options can help you finance a property, but they are structured differently. The key distinction is how the bank provides the financing and earns its return.
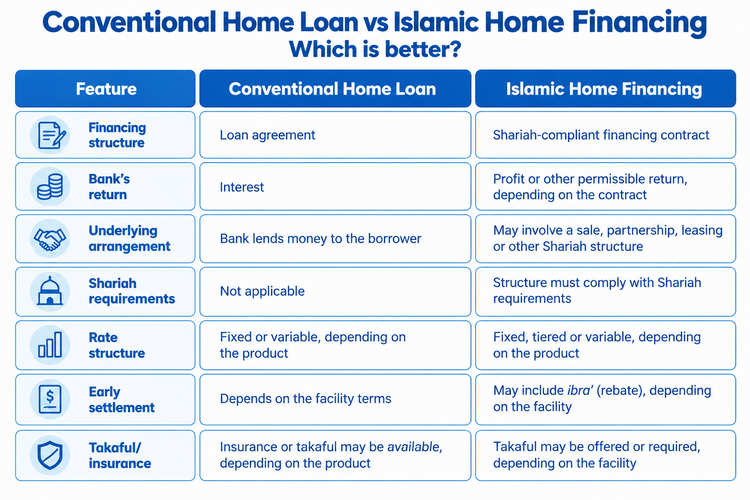
An Islamic home financing facility does not necessarily have a fixed monthly instalment. Some products offer fixed or tiered rates, while others use variable rates.
For example, Maybank’s Commodity Murabahah Home Financing-i offers fixed, tiered and variable rate options, while AmBank’s Home Financing-i uses a variable rate.
Early settlement terms also vary. Some Islamic financing products may provide an ibra’ or rebate when you settle early, but the applicable conditions depend on your financing agreement.
When comparing the two, look beyond the headline rate. Check the monthly instalment, total amount payable, fees, lock-in period and early settlement terms.
How Are Profit Rates Calculated?
When comparing Islamic home financing, you will usually see a profit rate instead of an interest rate. The rate represents the bank’s return under the Shariah-compliant financing arrangement.
The rate can be fixed, tiered or variable, depending on the product. If you choose a variable-rate facility, you may also come across the Standardised Base Rate (SBR).
1. What is SBR?
The Standard Base Rate (SBR) is the common reference rate used for new retail floating-rate loans and financing in Malaysia. It is linked to Bank Negara Malaysia’s Overnight Policy Rate (OPR).
As of 3 September 2026, the OPR is 2.75%.
Your actual financing rate may therefore be different from the SBR. For a variable-rate facility, changes in the reference rate can affect your financing rate and potentially your monthly instalments, depending on the product’s terms.
Before choosing a package, check:
- The applicable profit rate
- Whether the rate is fixed or variable
- The SBR and applicable spread, if relevant
- The ceiling profit rate, where applicable
- Your estimated monthly instalment
- The total amount payable over the financing tenure
- What happens to your instalment if the applicable rate changes
Understanding how the profit rate is set can help you anticipate changes in monthly repayments. Before choosing a package, check the SBR, applicable spread, ceiling profit rate, total amount payable, and repayment terms.
What Should You Consider Before Taking Islamic Home Financing?
Before choosing an Islamic home financing package, look beyond the profit rate. The financing structure, fees, repayment terms and property requirements can all affect the overall cost of buying your home.
1. Legal and documentation costs
Islamic financing can involve different contractual documents depending on the Shariah structure used. You may also need to budget for costs such as legal fees, valuation fees and stamp duty, where applicable.
Check the bank’s PDS and financing documents, so you know which costs apply to your facility.
2. Profit rate and ceiling rate
If the financing has a variable profit rate, check how the rate is calculated and what reference rate applies.
Some products also have a ceiling profit rate. For example, Maybank states that its Commodity Murabahah Home Financing-i has a Ceiling Profit Rate (CPR), which provides customers with a maximum cap on the total financing payment despite periodic changes in the SBR.
However, this is a feature of that particular product, not a standard feature of every Islamic home financing package.
3. Late payment charges
Islamic financing does not mean late payments are free of charges. Banks can impose late payment charges according to the terms of the financing facility.
Check your PDS to understand the applicable rate and how late payment charges are calculated.
4. Early settlement and lock-in period
If you plan to sell your property or refinance before the financing tenure ends, check whether your package has a lock-in period or early settlement charge.
This does not mean every Islamic home financing package has the same terms, so check your specific facility before signing.
5. Property use and eligibility
The property you want to finance must also meet the bank’s eligibility requirements. This is particularly important if you are buying a SOHO, shop house or mixed-use property.
Ask the bank whether your intended use of the property is permitted under the financing facility before committing to the purchase.
Who Can Apply and What Documents Do You Need?
Islamic home financing is not limited to Muslims. Eligibility depends on the bank, your financial circumstances and the property you want to finance. Some products accept individual and joint applicants, while eligibility for residents and non-residents can differ.
What documents might you need?
The exact list varies by bank and whether you are salaried or self-employed. You may be asked for:
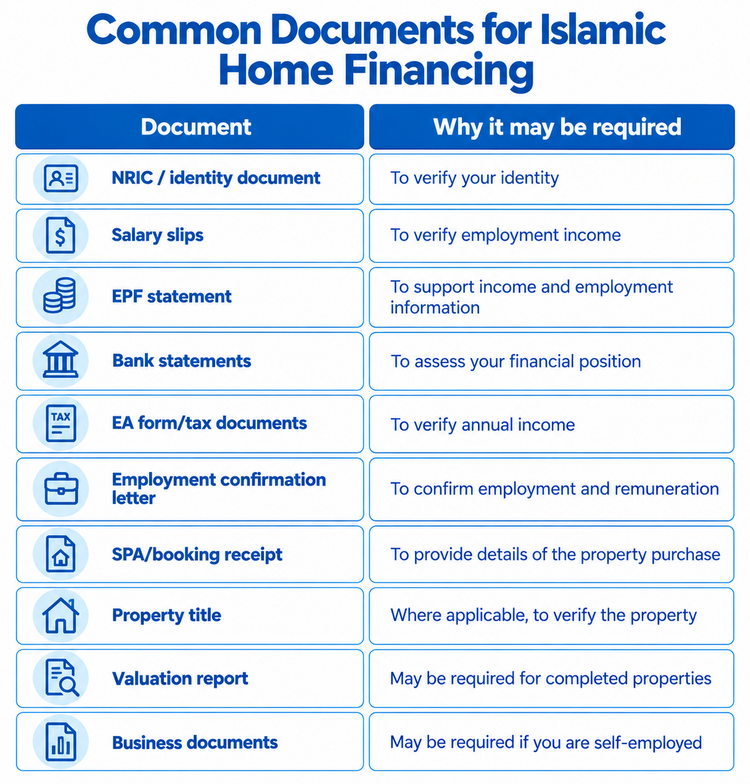
Prepare your income and property documents early. It can make the application process smoother, but always check the bank’s latest document checklist before submitting your application.
How to Apply for Islamic Home Financing?
Once you have found a property, the next step is to check your affordability, compare suitable financing packages and prepare your documents.
| Step | What to do |
| 1. Check your affordability | Work out how much you can comfortably put towards your monthly financing after accounting for your other financial commitments. |
| 2. Check your eligibility | Review the bank’s requirements for income, age, employment status and property type. |
| 3. Compare packages | Look at the profit rate, financing margin, tenure, monthly instalment, fees, lock-in period and early settlement terms. |
| 4. Prepare your documents | Gather your identity, income and property documents required by the bank. |
| 5. Submit your application | Apply to the bank and provide the required supporting documents for assessment. |
| 6. Review the offer | If approved, read the offer letter, PDS and financing agreement before accepting the facility. |
| 7. Complete the documentation | Sign the required financing and legal documents. The bank can then proceed with the financing and disbursement according to the agreed arrangement. |
Don’t compare packages based only on the advertised profit rate. Check the monthly instalment, total amount payable, fees and early settlement terms before making your decision.
Explore new projects for sale across Malaysia and find your new home.What Should You Compare Before Choosing a Package?
Don’t choose an Islamic home financing package based on the advertised profit rate alone. Compare the key terms below to understand what you could pay and what the facility allows.
| What to compare | Why it matters |
| Profit rate | Check whether it is fixed, tiered or variable and how it affects your repayments. |
| SBR and spread | For variable-rate financing, understand how changes in the SBR can affect your applicable rate. |
| Ceiling profit rate | Check whether the facility has a maximum profit rate or financing payment cap. |
| Financing margin | Find out how much of the property’s purchase price or value the bank can finance. |
| Financing tenure | A longer tenure can reduce your monthly instalment but may increase the total amount payable. |
| Monthly instalment | Check the initial payment and whether it can change if the applicable rate changes. |
| Lock-in period | Find out whether a charge applies if you settle or refinance the financing early. |
| Early settlement | Check whether ibra’ (rebate) applies and how it is calculated. |
| Takaful | Check whether MRTT, MLTT or another form of protection is required or optional, and factor the cost into your budget. |
| Fees and charges | Consider legal fees, valuation fees, stamp duty and other applicable charges. |
| Property eligibility | Make sure the property and its intended use meet the bank’s financing requirements. |
The terms can vary between banks and products. For example, Maybank and AmBank publish different Islamic home financing structures and product terms, so compare the full financing package, rather than relying on one headline rate.
Choosing the Right Islamic Home Financing for You
Choosing Islamic home financing involves more than comparing the advertised profit rate. Consider the financing structure, monthly instalments, tenure, financing margin, fees, Takaful requirements and early settlement terms before making a decision.
It is also important to read the PDS and financing agreement carefully so you understand the costs, repayment terms and other commitments involved. By comparing these factors, you can make a more informed decision and choose an Islamic home financing package that suits your property purchase and financial circumstances.
Ready to take the next step? Explore properties for sale and find a home that fits your budget and financing needs.