For landlords, receiving monthly rent can seem straightforward until tax filing season arrives. Rental income comes with tax responsibilities, and overlooking them can result in inaccurate filings or missed opportunities to claim allowable expenses.
Rental income from property in Malaysia is generally taxable, but landlords are not necessarily taxed on every ringgit collected. Certain expenses incurred in producing rental income may be deductible, meaning the amount considered for tax purposes can be lower than your gross rental receipts.
This guide explains how LHDN rental income is treated in Malaysia, what landlords need to declare, which expenses may be deducted, how to calculate net rental income, and what records you should keep.
Browse properties for rent in Malaysia and find a home that suits your needs.Do You Need To Declare Your Rental Income?
Rental income earned from property in Malaysia generally needs to be declared to the Inland Revenue Board of Malaysia (LHDN). This applies whether a landlord rents out an entire property or a single room, and regardless of whether renting is their main source of income.
Under paragraph 4(d) of the Income Tax Act 1967, rental income is generally treated as non-business income when the landlord simply lets the property without comprehensively and actively providing maintenance or support services. This includes common arrangements where tenants pay monthly rent to occupy a house or condominium.
For example, an individual earning a monthly salary who also receives RM1,500 in rent from a condominium must generally account for both income sources when filing their annual tax return. However, eligible rental expenses can be deducted when calculating net rental income.
Landlords should therefore include their rental earnings in their tax calculations, even when property letting is only a secondary source of income.
Is Rental Income Business Or Non-Business Income?
Not all LHDN rental income is treated in exactly the same way. Where a landlord lets real property and does not comprehensively and actively provide maintenance or support services, the income is generally treated as a non-business source under paragraph 4(d).
For example, a landlord who rents out a condominium for RM2,000 per month without providing additional services would generally earn non-business rental income.
However, if a landlord comprehensively and actively provides maintenance or support services, such as regular housekeeping, security, and other facilities management services, the rental income may instead be classified as business income under paragraph 4(a).
This classification is important because it determines how rental expenses and losses are treated when calculating taxable income.
Find new homes for sale in Malaysia and find one that fits your needs.What Rental Expenses Can And Cannot Be Deducted?
Landlords can generally deduct qualifying expenses that are wholly and exclusively incurred in producing rental income. However, certain costs, particularly initial expenses and capital expenditure, are not deductible when calculating net rental income.
Rental Expenses You Can Deduct
Depending on your circumstances, allowable expenses may include:
- Assessment tax and quit rent: Payments made for the assessment tax and quit rent on your rental property.
- Loan interest: Eligible interest on a loan used to purchase the rental property.
- Fire insurance: Fire insurance premiums paid to protect the property.
- Rent collection expenses: Costs incurred in collecting rental payments from tenants.
- Legal expenses: Qualifying legal costs incurred to enforce rent collection.
- Ordinary repairs: Expenses incurred to maintain the property in its existing condition.
- Tenancy renewal expenses: Qualifying costs associated with renewing a tenancy or obtaining a subsequent tenant.
Rental Expenses You Cannot Deduct
The following expenses are generally not deductible:
- Advertising for the first tenant: Initial advertising costs incurred to secure the property’s first tenant.
- Agent’s commission for the first tenant: Commission paid to obtain the first tenant.
- Legal fees for the first tenancy: Expenses incurred in preparing the initial tenancy agreement.
- Stamp duty for the first tenancy: Stamp duty associated with the initial tenancy agreement.
- Loan principal repayments: Repayments of the amount borrowed to finance the property.
- Capital expenditure: Costs that substantially improve, renovate, or alter the property rather than maintain its existing condition.
Understanding which expenses qualify for deductions helps landlords calculate their LHDN rental income accurately. In particular, eligible loan interest may be deductible, but loan principal repayments are not.
How Do You Calculate Net Rental Income For LHDN?
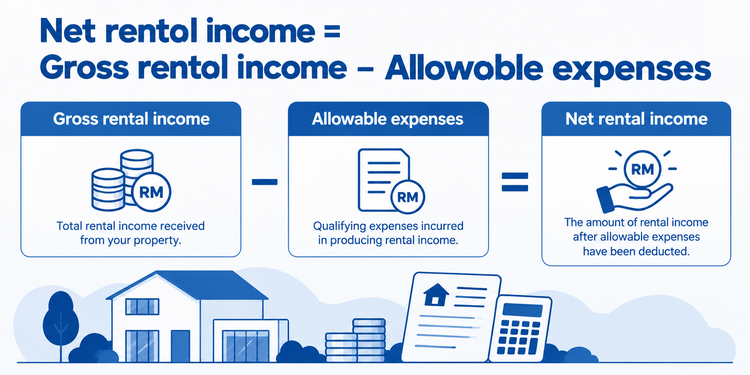
To calculate net rental income for LHDN, landlords must subtract qualifying expenses from their gross rental earnings. This helps determine the amount subject to tax.
The basic calculation is:
Suppose your property is rented for RM2,000 per month for the entire year:
Gross annual rental income:
RM2,000 × 12 = RM24,000
During the year, assume you incur the following allowable expenses:
| Expense | Amount |
| Assessment tax | RM1,000 |
| Quit rent | RM100 |
| Allowable repairs | RM3,000 |
| Eligible loan interest | RM5,000 |
| Total | RM9,100 |
Your net rental income would therefore be:
RM24,000 − RM9,100 = RM14,900
In this example, RM14,900 is the net rental income after the relevant allowable expenses, rather than the full RM24,000 received from the tenant.
Estimate your monthly home loan repayments with the Mortgage Calculator.How Do You Declare Rental Income To LHDN?
Declaring rental income correctly helps landlords meet LHDN requirements while claiming eligible deductions that can reduce the amount of rental income subject to tax.
Step 1: Calculate Your Gross Rental Income
Add up the total rental income received from each property during the relevant year of assessment. If you have more than one rental property, keep the calculations for each rental source separate.
Step 2: Add Up Your Allowable Expenses
Identify expenses that can be deducted from the rental income, such as eligible loan interest, assessment tax, quit rent, insurance, allowable repairs, and qualifying tenancy renewal expenses.
Step 3: Calculate Your Net Rental Income
Deduct the total allowable expenses from your gross rental income:
Net rental income = Gross rental income − Allowable expenses
This gives you the rental income after eligible deductions have been taken into account.
Step 4: Complete The HK-4 Working Sheet
Use LHDN’s Working Sheet HK-4: Computation of Statutory Income – Rents to record the rental income and allowable expenses and calculate the resulting statutory rental income.
Step 5: Enter The Rental Income In Your Tax Return
Transfer the relevant amount to the rental income section of your income tax return. The appropriate form depends on your circumstances, including whether you have business income.
Step 6: Submit Your Income Tax Return
Complete and submit your income tax return through the applicable LHDN filing method. Check that the rental income and deductions declared match your calculations and records.
Step 7: Keep Your Supporting Documents
Keep relevant documents and records for seven years. These may include tenancy agreements, rental payment records, assessment tax and quit rent receipts, loan interest statements, insurance records, and invoices or receipts for expenses claimed.
Following these steps gives landlords a clear process for reporting rental earnings and ensures the figures entered in their tax return are properly supported.
What Happens If Your Rental Property Makes A Loss?
A rental property can make a loss when allowable expenses exceed the rental income earned during the relevant period.
However, landlords should not automatically offset a rental loss against salary or other income. The treatment of losses can differ depending on whether the letting is treated as a business source under paragraph 4(a) or a non-business source under paragraph 4(d).
If you have several rental properties, substantial expenses, or an arrangement that may constitute a rental business, professional tax advice may help determine the correct treatment.
How Much Tax Do You Pay On Rental Income?
There is no separate flat rental income tax rate for resident individual landlords in Malaysia.
Instead, your net rental income forms part of your income for tax purposes. The final amount of tax payable depends on factors such as your other income, allowable deductions, applicable tax reliefs, and resulting chargeable income.
For the Year of Assessment 2025, LHDN’s published resident individual income tax rates range from 0% to 30%, depending on chargeable income.
Are There Rental Income Tax Exemptions Or Incentives In 2026?
Landlords should be careful when reading older information about Malaysian rental tax incentives.
Malaysia previously offered a 50% income tax exemption on qualifying residential rental income, subject to specific conditions. However, the exemption applied to YA 2018 only and has since expired. There is no blanket residential rental income exemption for YA 2026.
Rather than relying on previous incentives, landlords should focus on calculating their current rental income accurately and claiming allowable expenses supported by appropriate documentation.
Understanding LHDN rental income requirements helps landlords declare their earnings correctly, claim eligible deductions, and avoid unnecessary tax complications. Staying informed about current rules also makes it easier to manage rental income responsibly and meet annual tax obligations.
Need practical advice on buying, selling, or owning a home? Explore Property Guides for useful property information on iProperty Malaysia.