Should you choose MRTA or MLTA for your home loan? Which one costs less? What happens to the cover if you sell your property or repay the loan early? These are some of the questions you may have when deciding on mortgage protection.
MRTA and MLTA both provide protection linked to your home loan, but they work differently. MRTA generally provides reducing cover, while MLTA generally keeps the insured amount level throughout the policy term.
In this guide, we’ll explain how MRTA and MLTA work, compare their coverage and costs, and look at what happens if you sell, refinance, or settle your home loan early. This will help you understand your options before choosing a policy.
<a href=”https://www.iproperty.com.my/financing/mortgage-calculator/”><strong>Calculate your monthly mortgage repayments with our Mortgage Calculator.</strong></a>What is MRTA and how does it work?
MRTA (Mortgage Reducing Term Assurance) is designed to help cover your home loan if you die or suffer Total and Permanent Disability (TPD) during the coverage period. The insured amount reduces over time, rather than staying at the original loan amount.
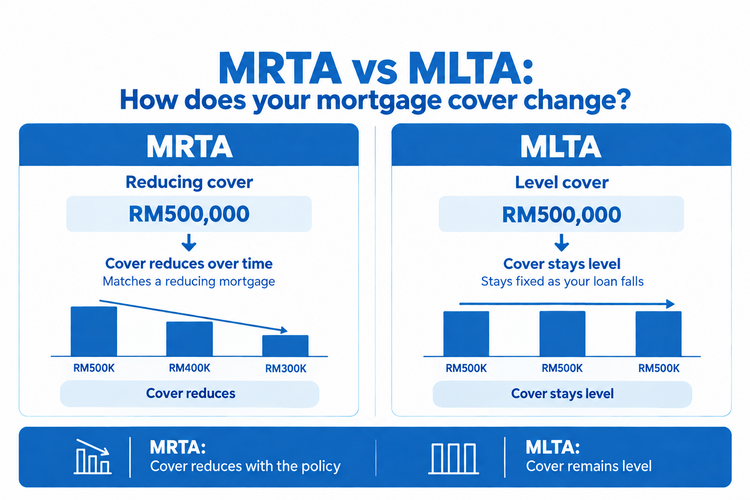
For example, if you take an MRTA plan with an initial cover of RM500,000, the cover is scheduled to reduce throughout the policy term. Under a current Manulife MRTA plan distributed by Bank of China Malaysia, the RM500,000 initial face amount reduces monthly.
If a covered event occurs, the applicable reduced amount is used towards the outstanding home loan, subject to the policy terms. This means MRTA is primarily designed to protect the mortgage rather than provide a fixed cash benefit throughout the loan term.
The reduction in cover is based on the policy schedule, so it may not exactly match your actual outstanding loan at every point. Maybank, for example, notes that its illustrated reducing sum covered assumes the insured amount and policy term match the loan and that there is no increase in the interest rate.
What does MRTA cover?
MRTA commonly covers death and TPD. If you make a valid claim, the benefit can be used to settle the outstanding home loan, subject to the policy terms.
The exact coverage, exclusions, and TPD conditions vary by plan, so check these details before buying.
How is the claim used to settle the mortgage?
MRTA is designed to protect the home loan. If a covered event occurs, the insurer pays the applicable benefit according to the policy and any assignment to the lender. The amount is then used towards the outstanding loan.
For example, the current Manulife MRTA plan distributed through Bank of China Malaysia provides for the benefit to be paid to the bank to cover the outstanding loan facility. Any applicable balance is dealt with according to the policy terms.
This means your family may no longer have to shoulder the covered portion of the mortgage, depending on the claim and policy terms.
What is MLTA and how does it work?
MLTA (Mortgage Level Term Assurance) provides a fixed amount of cover throughout the policy term. Unlike MRTA, the cover does not reduce as you continue repaying your home loan.
MLTA commonly covers death and TPD. If you make a valid claim, the benefit can be used to settle the outstanding home loan, subject to the policy and assignment terms.
A current Manulife MLTA plan available through Bank of China Malaysia, for example, provides level cover and allows the bank to use the benefit towards the outstanding loan. This means the insured amount can become higher than your outstanding loan as you make repayments.
For example, if you have RM500,000 of MLTA cover and your outstanding loan falls to RM300,000, the policy can still provide the stated level cover, subject to its terms.
Does MLTA automatically include savings or investment benefits?
MLTA is not automatically a savings or investment plan. For example, the current Manulife MLTA plan available through Bank of China Malaysia is a single-premium term life insurance plan.
Features such as cash value, refunds, or maturity benefits depend on the specific plan, so check the Product Disclosure Sheet before choosing.
<a href=”https://www.iproperty.com.my/property-for-sale”><strong>Explore properties for sale and find your next home on iProperty. </strong></a>What is the difference between MRTA and MLTA?
The main difference becomes clearer when you look at what happens to your mortgage cover as you repay the loan. With MRTA, the insured amount reduces over time. With MLTA, it stays level throughout the policy term, subject to the policy terms.
- Your mortgage falls, but the cover works differently
With MRTA, the insured amount reduces according to the policy schedule as the mortgage progresses. With MLTA, the insured amount stays level even as you continue repaying the loan.
This means MLTA can provide a higher insured amount than the remaining mortgage later in the loan term.
For example, if you have RM500,000 of MLTA cover but owe RM300,000 on your home loan when a valid claim occurs, the policy still provides the level insured amount, subject to its terms and assignment arrangement. Any amount remaining after the lender’s entitlement is dealt with according to the policy.
- The price should be compared against the cover you receive
MRTA may cost less because the insured amount reduces over time, but you should compare actual quotations rather than assume one option is always cheaper.
The cost can vary based on factors such as your age, coverage amount, policy term and underwriting. Current Manulife MRTA and MLTA disclosures, for example, state that premiums can vary based on factors including age, face amount, coverage term and underwriting.
A more useful comparison is to look at how much you pay and what protection you receive throughout the loan term, rather than comparing the premium alone.
- A single premium does not mean the cost is lower
Both MRTA and MLTA can be offered as single-premium plans. The current Manulife plans available through Bank of China Malaysia are examples of this.
Some lenders may also allow the premium to be added to the home financing. Maybank, for example, allows its MRTA single premium to be capitalised into the mortgage, subject to its terms.
If you finance the premium, remember that you are also borrowing that amount.
- Selling or refinancing can change what happens to the policy
If you plan to sell your home or refinance, do not assume that your MRTA or MLTA will automatically move to the new property or lender.
Check the policy’s rules on cancellation, surrender and assignment, and ask the existing and new lender how the cover will be handled. These arrangements depend on the specific policy and financing terms.
How much does MRTA or MLTA cost?
The cost of MRTA or MLTA varies from person to person. Your age, coverage amount, policy term and underwriting can all affect the premium. Current Manulife disclosures, for example, state that the premium is determined based on factors such as age, face amount, coverage term and underwriting.
When comparing quotations, look beyond the premium. Check the total amount you will pay, how long the cover lasts and what level of protection you get. A lower premium is not necessarily better if it provides less cover or a shorter term.
What if the premium is added to your home loan?
Some banks allow the mortgage protection premium to be included in your home financing. Maybank, for example, allows its MRTA single premium to be capitalised into the mortgage, subject to its terms.
This means you do not have to pay the full premium upfront, but you are also borrowing that amount. You should therefore check how adding the premium affects your total financing cost and monthly repayments before making a decision.
What happens to MRTA or MLTA if you sell or refinance?
Selling your property, refinancing your home loan or paying off the mortgage early can affect your mortgage protection.
What happens next depends on the policy terms and how the policy is assigned to your lender. Current MRTA and MLTA product documents include specific rules for cancellation, surrender and assignment.
If you sell your property
When you sell the property and settle the home loan, the lender’s interest in the policy may also need to be dealt with. Depending on the plan, you may be able to surrender the policy or receive a cash value, but this is not automatic.
Ask the insurer what happens to the policy after the loan is settled and whether any amount is payable to you.
If you refinance
Refinancing means your existing home loan is replaced by a new financing arrangement. Before cancelling your existing MRTA or MLTA, check whether the policy can remain in force or be reassigned to the new lender.
Do this before taking new cover so you do not cancel an existing policy without understanding the financial implications.
If you repay the loan early
Paying off your mortgage before the end of the policy term does not necessarily mean you will receive your premiums back.
Some policies provide a surrender or cash value, but the amount and conditions vary. For example, current Manulife MRTA and MLTA disclosures set out specific cancellation and cash-value provisions, including different treatment where the premium has been financed.
Before settling the loan early, ask the insurer what will happen to the policy and whether keeping, surrendering or replacing the cover makes the most sense.
What about MRTT and MLTT?
If you are taking Islamic home financing, your bank may offer MRTT or MLTT instead of conventional mortgage insurance. MRTT provides reducing cover, while MLTT keeps the sum covered level throughout the Takaful term.
The choice is similar to MRTA vs MLTA. You are comparing reducing or level protection, but through a Takaful arrangement. Contribution and financing arrangements can also vary between plans.
If you are offered MRTT or MLTT, compare the cover amount and term, contribution, death and TPD benefits, exclusions, and what happens if you settle or refinance your financing.
What should you check before buying mortgage protection?
Before choosing MRTA, MLTA, MRTT or MLTT, compare the quotation with the Product Disclosure Sheet. Do not choose based on the product name or premium alone.
Check these points before you decide:
- How much cover do you get? Check the starting sum assured and whether it reduces over time.
- How long does the cover last? Make sure the policy term matches the period you need protection.
- What will you actually pay? Check the total premium or contribution, not just the amount you pay upfront.
- Can the premium be added to the loan? If it can, check how this affects your total financing cost.
- What happens if you make a claim? Check the death and TPD benefits, exclusions and claim conditions.
- What happens if you settle the loan early? Find out whether the policy can continue and whether any surrender or cash value is available.
- What happens if you sell or refinance? Check whether the policy can be continued, reassigned or surrendered.
- Who receives the benefit? Understand the lender’s rights under any assignment and what happens to any remaining amount.
- Do you already have enough life cover? Consider your existing insurance before taking additional mortgage protection.
These details can make a bigger difference to your decision than simply choosing between “MRTA” and “MLTA”. Always refer to the relevant Product Disclosure Sheet and policy or certificate wording for the terms that apply to your plan.
Which is better: MRTA or MLTA?
MRTA and MLTA serve the same broad purpose, but they provide mortgage protection differently. MRTA reduces the insured amount over time, while MLTA keeps it level throughout the policy term.
Your decision should come down to the type of cover you need, the cost you are comfortable with and the terms of the specific policy. If you already have life insurance, consider that existing cover too and check whether your lender has any specific requirements.
Rather than choosing based on the product name alone, compare the coverage, total cost, claim benefits and what happens if you sell, refinance or settle your home loan early.
Looking for more home financing and property tips? Explore iProperty’s property guides for useful advice on buying, financing and owning a home.
Looking for your next home? Discover new launch projects in Malaysia to find a property that suits your needs and budget.